
Paying a little extra towards a home loan does more than most people expect. Every rupee goes straight at the balance. It then stops interest building on that rupee for the rest of the term.
There is a catch. The bank will ask whether you want a shorter loan or a smaller EMI. One of those saves roughly twice as much as the other.
Your loan
What you borrowed, not the price of the house.
Leave at zero if the loan is new.
Your extra payment
On top of your EMI.
The same yearly amount does more when it goes in monthly.
Used to check whether clearing the loan beats investing the same money.
Your loan ends
4 years and 5 months sooner
and you save ₹13,89,250 in interest.
Keep the EMI, shorten the loan
Loan closes in 15 years and 7 months
₹13,89,250interest saved
Keep the term, cut the EMI
EMI falls to ₹8,189 by the end
₹6,04,896interest saved
Shortening the loan saves ₹7,84,354 more than cutting the EMI.
Shorter loan or smaller EMI
This is the choice the bank gives you. It is worth lakhs. Take a ₹50 lakh loan at 8.5% over 20 years, with ₹5,000 paid extra each month.
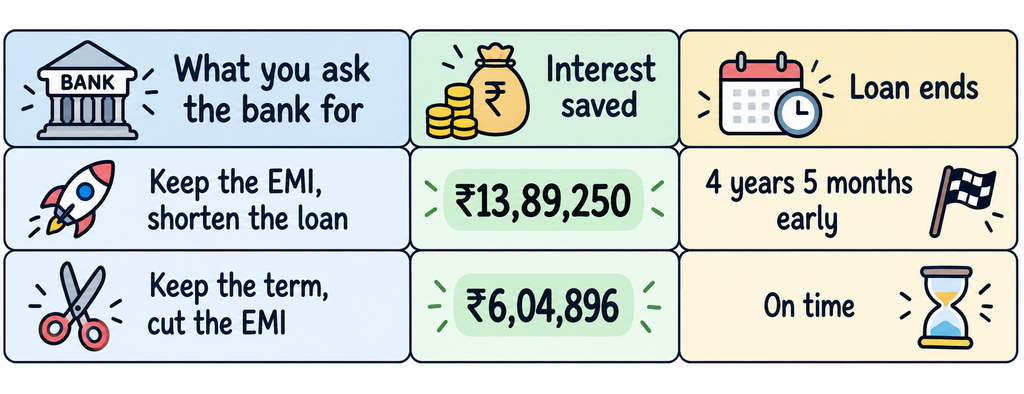
Same money. More than twice the saving. Cutting the EMI feels better each month, which is why people pick it. But it leaves the loan running the full twenty years. Interest keeps building the whole time.
Or do not pay it off at all
There is a fair case for investing the money instead. The test is simple. If you expect to earn more than your loan charges, investing wins. If not, clearing the loan wins. The tool checks this properly. It compares what you hold on the first end date either way. It also counts the EMI you free up when the loan closes early. On the figures above the switch comes right at the loan rate. That is what you would expect. Below it, paying down the loan wins. Above it, investing does.
One thing the sums cannot weigh. Clearing a loan is certain. The growth rate is a hope.
Three things to know
- There is no charge for paying early. Since 1 January 2026 a bank cannot charge you for clearing a floating rate home loan early. That covers part payment and full. A fixed rate loan still can.
- Early rupees count most. An extra payment in year two saves far more than the same amount in year fifteen. It stops interest building for longer.
- Monthly beats yearly. The same yearly sum does more when it goes in each month. It starts cutting the balance sooner.
The free home calculator works the other side of this, investing alongside the EMI instead of against it. The debt payoff calculator decides which loan to clear first when you have several.
This calculator is for learning. It is not advice for your own case. No bank, fund or firm is named or backed here. It assumes your rate does not change. It assumes every payment lands on time. It also assumes the bank puts your extra payment against the balance straight away. A floating rate loan will move, which changes all of this. Growth is a number you choose, not a forecast, and money in shares can fall. Tax on your gains is not counted. Ask your own bank how it treats part payments before you rely on these figures. For advice on your own money, speak to a SEBI-registered investment adviser.