
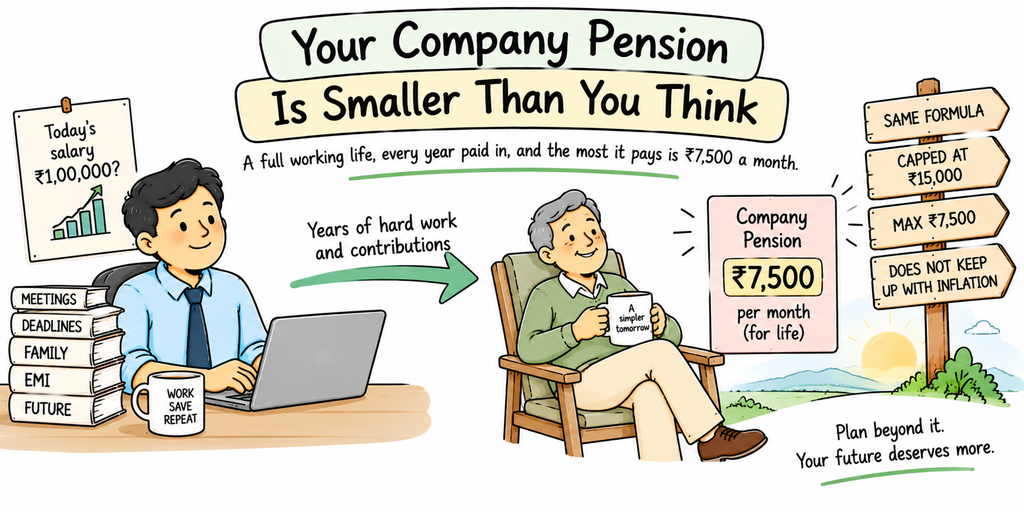
If you work for a company in India, a slice of your salary goes into a pension every month. You will get that pension for life once you turn 58.
Most people have never worked out how much it will be. It is smaller than almost everyone expects.
How the amount is worked out
There is one formula, and it has only two things in it.
Monthly pension = your pensionable salary, times your years of service, divided by 70.
Your years of service is simply how long you paid in. If you cross 20 years you get two extra years added as a bonus, and the count stops at 35. Pensionable salary is the part that catches people out, so it gets its own section.
The number your pension is really based on
It is not your salary. It is capped at ₹15,000 a month. You may earn ₹50,000. You may earn ₹3 lakh. For this pension, the sum is done on ₹15,000 either way. That single line explains everything that follows.
So here is what you will actually get
| Years you paid in | Counted as | Monthly pension for life |
|---|---|---|
| 10 years | 10 | ₹2,143 |
| 20 years | 22 | ₹4,714 |
| 25 years | 27 | ₹5,786 |
| 30 years | 32 | ₹6,857 |
| 35 years | 35 | ₹7,500 |
Read the last row. A full working life, every year paid in, and the answer is ₹7,500 a month. That is the most this pension pays anybody. There is a floor too. Nobody gets less than ₹1,000 a month.
And it does not grow with prices
The amount is fixed. Prices are not.
- In 10 years, ₹7,500 will buy what ₹4,188 buys today.
- In 20 years, what ₹2,339 buys today.
- In 25 years, what ₹1,747 buys today.
So it is a small amount now, and a very small amount later.
A way to see what it is really worth
Ask a different question. How much would you need saved to pay yourself the same amount? To draw ₹7,500 a month safely from your own savings, you would need about ₹25.7 lakh. That is the whole value of this pension, in today’s money. It is not nothing. It is also not a retirement.
The higher pension option has closed
You may have read something else. That you can ask for the sum to be done on your real salary instead of ₹15,000. That was true for a while. It is not true now. Plenty of pages still say it is.
Here is the short history.
- In November 2022 the Supreme Court said some members could opt for a pension based on their actual salary.
- Applications opened, and the date was pushed back three times. It finally shut on 11 July 2023.
- A new pension scheme was notified in 2026, and it removes that option altogether.
So there is nothing to apply for. If a page or an agent tells you to send in a form now, they are out of date. That tells you what the rest of their advice is worth.
If you did apply before the window shut, your case has almost certainly been decided. Around 15 lakh applications came in and only about 11,600 were still waiting as of August 2026. You can check yours on the member portal.
Two things that have not changed
The new scheme worried a lot of people. So it is worth being clear.
Existing pensions carry on. Already drawing one, or already a member? Nothing stops. Nothing is worked out again. The formula is the one above.
There is talk of raising the ₹15,000 cap to ₹25,000. That would lift the maximum pension to about ₹12,500 a month. It is a proposal and nothing more. Do not plan around it.
What to do with this
- Work out your own figure from the table. It takes a minute and most people are surprised.
- Treat it as a small bonus, not a plan. It might cover the electricity and the groceries. It will not cover a life.
- Do not count it twice. The pension and the provident fund balance are two different things from the same deduction. People often add both in as if each were their retirement.
- Work out what you actually need. The retirement calculator gives you the real number. Subtract your pension from it and save for the rest.
- If you are still working, use the provident fund properly. Putting extra in is the best safe return most salaried people can get. The ten years before retirement shows the limits on it.
None of this is a complaint about the scheme. It pays something to a great many people. It never fails.
The danger is quieter than that. It is the person who spends thirty years assuming a pension is coming. And finds out what it comes to in the month it starts.
This article is for learning. It is not personal financial advice. The figures assume the sum is done on the capped salary of ₹15,000, which is true for most members. They ignore the different rules for service before 2014. Pension rules are set by the government and changed in 2026. Check your own position with your employer or the pension office. The inflation rate used is an example to show how the sums work, not a forecast. For advice about your own retirement, speak to a SEBI-registered investment adviser.