
A home loan has two halves. The EMI buys the house. Everything on top of what you borrowed is the price of borrowing it.
Here is the idea. Run a small investment alongside the EMI, for the same years. By the time the loan ends you own the house, and the money it cost you is back in your hands. Only the gains count. The money you put in was always yours, so it recovers nothing on its own.
Your home loan
What you borrowed, not the price of the house.
Leave at zero if the loan is new. The investment runs for the years still left.
Your investing
Before charges and tax. Nobody can promise this. Put in a smaller number and watch what happens.
To get every rupee back, invest
₹19,810
Every month, on top of your EMI of ₹43,391.
Get back what you borrowed
Your gains alone come to ₹50,00,000
₹9,51122% of your EMI
Get back only the interest
Your gains alone come to ₹54,13,879
₹10,29824% of your EMI
Get back every rupee you paid
Your gains alone come to ₹1,04,13,879
₹19,81046% of your EMI
Why the monthly figure is so small
On a ₹50 lakh loan over 20 years you pay the bank about ₹1.04 crore. Getting all of it back sounds impossible on an ordinary salary. It is not, and here is why.
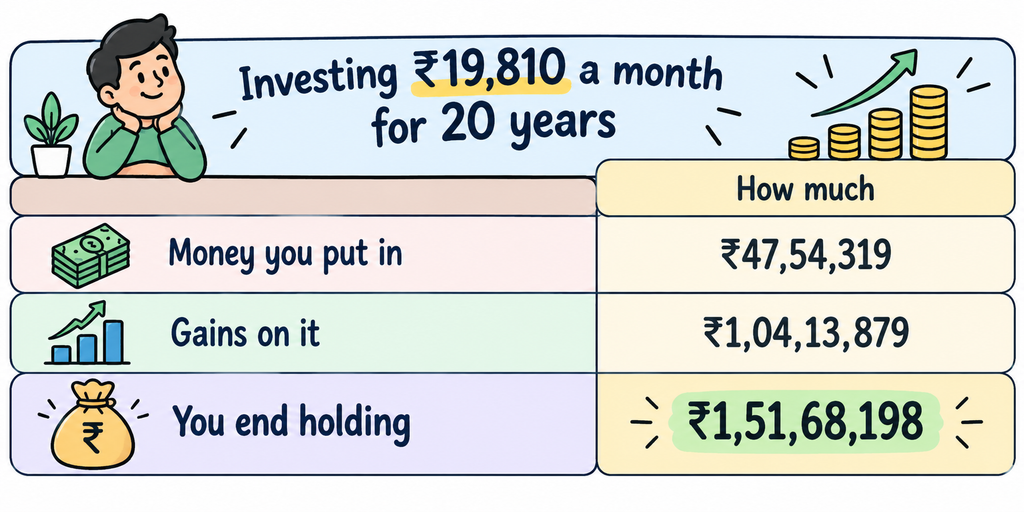
Read the middle row. The gains alone come to ₹1.04 crore, which is what the house cost you. Your own ₹47.5 lakh is still there on top. That is the point. Money you put in was always yours, so it recovers nothing by itself. That is the same force working against you inside the loan. Here you have it on your side instead, for the same twenty years.
When this does not work
- If you expect to earn less than your loan charges. Then the same money does more inside the loan. Clear the debt instead. The calculator says so when you set it that way.
- If you cannot keep it up. This only works if the money goes in every month for the full term. A plan you stop after four years gets you a fraction of the way.
- If you start late. With five years left the figures are several times larger, because almost all of it has to be your own money.
Two honest notes
The house is not really free. You still paid for it. What you have done is end the twenty years with the money back as well as the house. And the growth rate is a hope, not a promise. Markets do not rise in a straight line. Drop the rate to 8% and watch every figure move.
The down payment calculator works out what you need before any of this starts. Rent or buy asks whether to take the loan at all, and what a credit score is worth covers the rate you are offered.
This calculator is for learning. It is not personal financial advice, and no bank, fund or firm is named or backed here. Growth is a number you choose, not a forecast, and money in shares can fall. It assumes you invest every month without a break, that your loan rate does not change, and that you make no part payments. Tax on your gains is not counted, so aim a little above the target. A floating rate loan will move, which changes both the EMI and the interest. For advice on your own money, speak to a SEBI-registered investment adviser.