
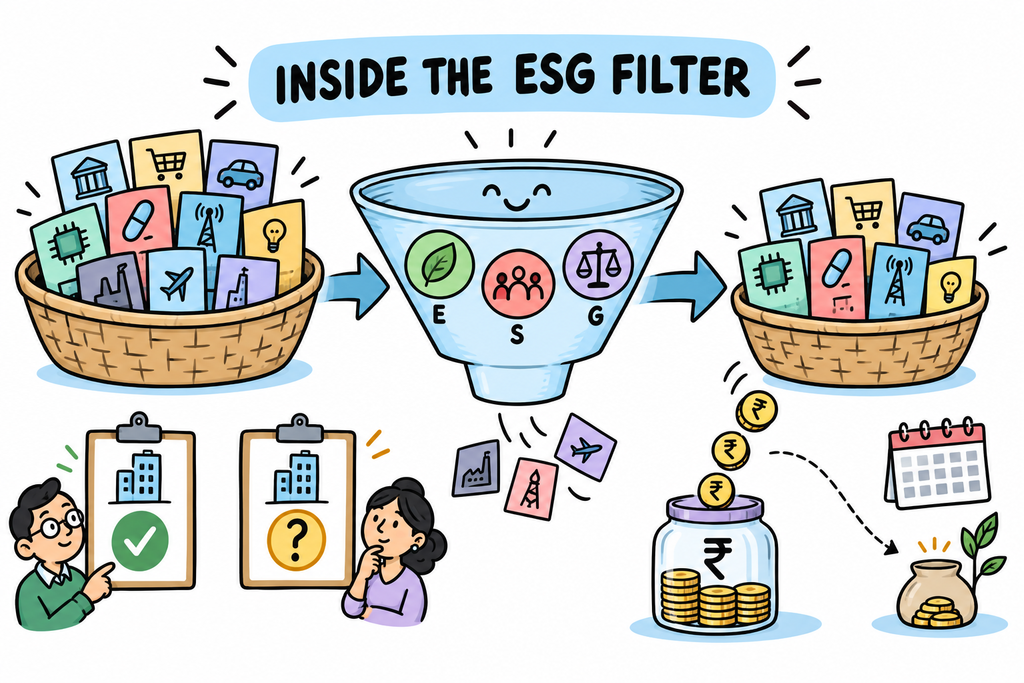
You may have seen a fund with the letters ESG in its name. The person selling it will say it puts your money into good companies.
Most people nod and move on, because the three letters explain nothing. So let us start there.
What the three letters mean
ESG stands for Environment, Social and Governance. They are three ways of judging a company on something other than profit.
- Environment. What the company does to the air, the water and the land. Does the factory dump waste into a river? How much power does it use, and where does that power come from?
- Social. How it treats people. Its workers, the people who buy from it, and the town it sits in. Are the factories safe? Are the wages fair? Does it use child labour anywhere down the line?
- Governance. How honestly it is run at the top. Are the accounts truthful? Does one family take decisions that hurt small shareholders? Has the boss been caught doing something he should not have?
Of the three, the last one should matter to you even if the first two do not. A company that lies in its accounts will lose your money. That is not about being good. That is about not being cheated.
What such a fund actually does
A normal equity fund buys shares in many companies. You own a small slice of each one.
An ESG fund does the same thing, with one extra step. Before it buys, it checks each company against those three tests. Companies that score badly are left out. Companies that score well are kept in.
That is the whole idea. Same investing, with a filter on the front.
The usual companies left out are tobacco, gambling, weapons, and sometimes coal or oil. Different funds leave out different things, which matters more than it sounds, and we will come to it.
Who decides which companies are good?
This is where it gets shaky.
Companies are given a score by rating firms. The fund then picks from the ones that score well. So the whole thing rests on those scores being right.
Some researchers at a university in America tested this. They took the same companies and compared what different rating firms said about them. If the firms agreed perfectly the answer would be 1. They agreed 0.61 of the way.
Now compare that with credit ratings, the scores that say whether a company can repay its loans. Those firms agree 0.99 of the way. Almost completely.
So a credit rating measures something real. An ESG score is closer to an opinion. One firm may call a company good. Another may throw the same company out.
That does not mean anyone is lying. It means the word “rating” sounds far harder than the thing actually is.
In India, the choice is narrower than you think
There is a rule here that shapes what these funds can own.
An Indian ESG fund must put at least 65% of its money into companies that have had their environment and social record checked by an outside auditor. Right now only the biggest listed companies have had that done. The rule is slowly being spread to smaller ones.
So the fund is choosing from India’s largest companies, and then dropping a few of them.
Which means what you are buying looks a lot like a plain big company fund. Not something new. The same thing, minus a few names.
What the filter costs you
Every fund charges you a fee each year. It is taken out quietly, so most people never feel it.
These funds charge about 0.85% to 1.4% a year. A plain index fund charges about 0.2%. That gap looks tiny. Over a working life it is not.
Put away ₹10,000 a month for twenty five years, and say your money grows 11% a year before fees.
- Plain index fund, fee 0.20%: you end with ₹1.54 crore.
- ESG fund, fee 0.85%: ₹1.37 crore.
- ESG fund, fee 1.10%: ₹1.32 crore.
- ESG fund, fee 1.40%: ₹1.25 crore.
At 1.10% the extra fee takes ₹22.1 lakh from you. That is about 14% of everything you would have had.
And you pay it every year, whether the filter does any good or not.
Not all of them cost that much. At least one in this group is priced close to an index fund. So check the fee first, not last. The compound interest calculator will show you the gap on your own numbers.
Does your money actually do any good?
Now the question nobody asks. Say the filter works exactly as promised. Does the company you refused to buy feel anything?
Almost certainly not, and here is why.
When you buy shares of a company on the market, the company does not get your money. You are buying from another investor who wants to sell. Your money goes to that person. The company never sees a rupee of it.
So refusing to buy a company’s shares takes nothing away from it. And buying them hands it nothing.
Big investors can push a company. They vote at meetings, they lean on the board, and they can make it harder for a company to raise fresh money. That is real. But none of it is what happens when you put ₹5,000 a month into a fund.
So what are you buying? A set of companies you feel alright about owning. That is a real thing and it may be worth money to you. It is not the same as changing how those companies behave.
So should you buy one?
If it truly bothers you to own a piece of a tobacco company, then buy one. Sleeping well is worth something. Just go in with your eyes open.
- Read the list of what it leaves out. It is published. Some funds drop far less than the name suggests, and the list may not match what you care about at all.
- Check the fee against a plain index fund. Every time. One per cent a year is not a small thing, as the numbers above show.
- Expect it to move like any other big company fund. It will not hold up better when markets fall. It is not something separate.
- Do not treat it as your good deed. If you want to do good, giving money away does more, and does it straight away.
Maybe the honest answer is that you wanted the returns, and feeling good was a bonus. If so, a plain index fund plus a donation somewhere will give you more of both.
None of this says you are wrong to care where your money sits. It says know what you are buying. Here it does less than the name promises, and costs more than the plain version.
This article is for learning. It is not personal financial advice and it is not a recommendation of any fund or company. The fees quoted are the range seen in this group of funds in India at the time of writing, and they change. Check the current figure for any fund you look at. The study on rating firms looked at global firms, not Indian ones. The growth rate used is an example to show how the sums work, not a promise. The rules for these funds are set by SEBI and are still being brought in. For advice about your own money, speak to a SEBI-registered investment adviser.